The Local Source for News and Information Since 1980
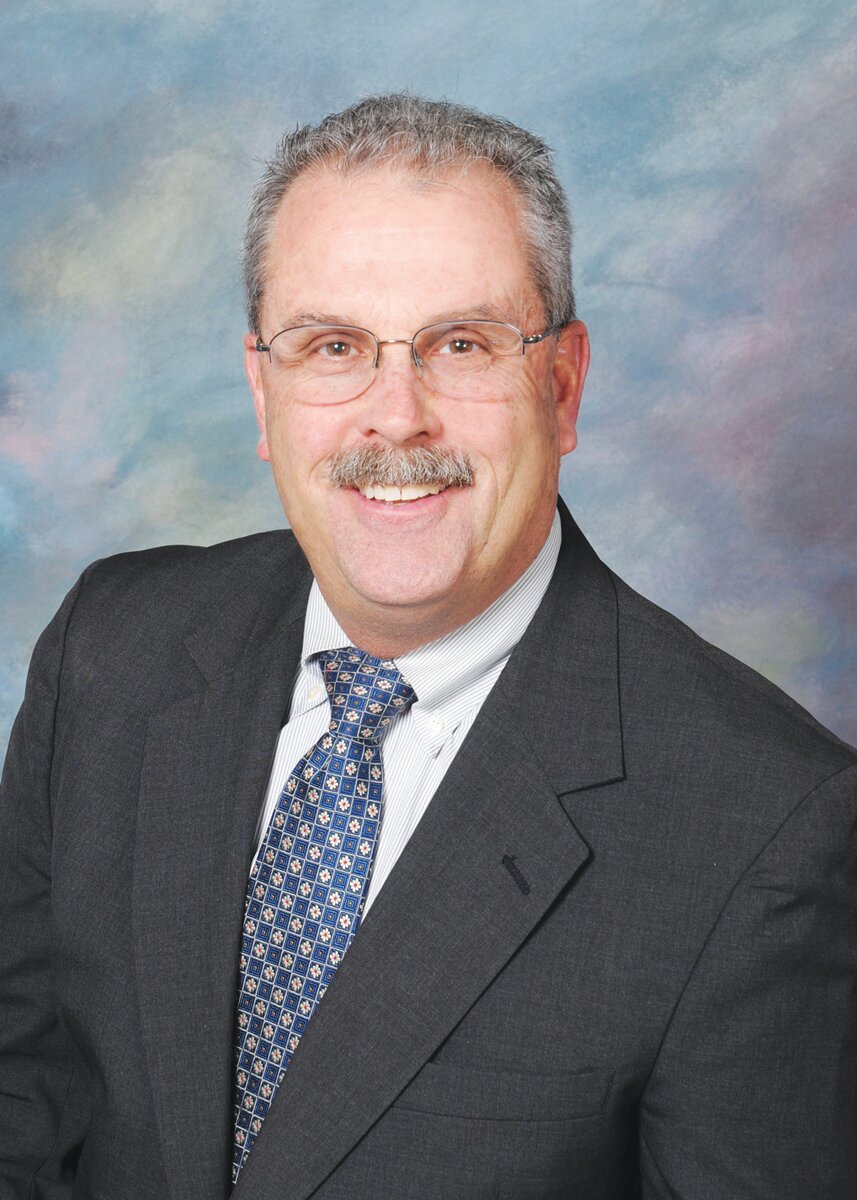
On Monday March 4, 1985, I walked into the offices of United Mortgagee in Severna Park and began my career in the residential lending business. Except for 2.5 years as Chief Lending Officer of Provident State Bank, I have been originating residential mortgages ever since.
With basic knowledge of what a residential loan officer, did Tom Casey, the branch manager responsible for my hiring, assured me that I would do fine. My prior experience selling Motorola 2 Way radio systems plus my five years experience as a part time real estate agent was a good foundation. Tom assured me that he would teach me the business. Here I am 40 years later.
When my journey began, mortgage rates were in the 12 to 13 percent range, down from a high of 18 to 19 percent in 1980. Since 1979 they had been in double digits and remained there until 1990, when they decreased to single digits, hitting bottom at 2.25 percent in 2021, the lowest fixed mortgage rates in history. It is easy to understand how mortgage rates influence the lack of inventory of homes for sale. What homeowner wants to give up a sub 4 percent mortgage so they can pay 7 percent on a new mortgage?
As the effects of the pandemic pushed the unemployment rate to 14 percent and inflation rate to 9.1 percent, the Federal Reserve responded by methodically lowering the Fed Funds rate to .25 to .50 percent in March of 2022, believing that the spike in inflation was “transitory” and Americans had to get back to work and jump start the economy. At the same time, the yield on the 10-year treasury bond, the best barometer for tracking mortgage rates dropped .5 to 1.2 percent. Both of these factors set the table for mortgage rates to drop to historically low levels. Monetary policy and the subsequent impact on interest rates was unique during this time. Selfishly I say that I am glad I was able to profit from it and help many first-time home buyers realize their dream of homeownership.
The Federal Reserve has set 2 percent as an acceptable rate of inflation and has managed the Fed Funds rate to achieve that end. In September of last year, prior to the election the Fed felt comfortable in lowering the Fed Fund rate .5 percent in September 2024 and again by .25 percent in November 2024 and .25 percent in December 2024.
But the bond market reacted differently with the yield on the 10-year treasury going in the opposite direction. Investors were concerned about the negative impact that President-elect Trump’s economic policies could have on inflation. The 10-year rate climbed from a low of 3.6 percent in mid September 2024 to 4.4 percent in December 2024 and has been in the 4 to 4.5 percent range since.
Investors, not the Federal Reserve or President Trump, are controlling mortgage rates. They are requiring a higher return on their investment to offset the effect of inflation.
Inflation diminishes the purchasing power of an investment at points in time in the future. For example: A person has $1,000 and can purchase 10 widgets at $100 a piece today. Instead of buying widgets they could invest $1,000 for a fixed term of 1 year and will be paid 10 percent interest receiving a total of $1,100 at the end of the 1-year period. If the cost of a widget goes increases to $110 in a year (10 percent inflation) the cost of 10 widgets is $1,100. The same amount the investor received by investing instead of buying widgets a year ago. They did not accomplish anything by waiting or saving.
Investors in long term US government bonds are guaranteed to get their money back as long as the US Government remains solvent. Investors in mortgage-backed securities do not have this same assurance. People do default on their mortgages, and do pay off their mortgages early, either by sale or refinance no longer paying interest to the investor. The risk of default and prepayment of mortgage-backed securities is offset by a higher rate than 10-year treasuries. Mortgage-backed securities usually yield about 2 to 2.5 percent more than the 10-year treasury yield.
Since President Trump’s inauguration, interest rates have gone up even as the Fed has lowered the short-term Fed Funds rate. Mortgage rates have not fallen, nor will they as long as the Trump administration advances policies that are inflationary. Broad based tariffs are inflationary in many different ways. Decreasing the US work force by removing employees willing to work for a wage less than what American workers will accept will drive up labor costs and thus the cost of goods and services. Why not find a way to legitimize those who are law abiding, tax paying contributors to our economy? That is a subject for another article.
It does not matter how you may feel about the “politics” of the Fed and inflation. This is how the market works. Those with the money willing to invest in mortgage-backed securities believe this. And they are the ones who want to be compensated when inflation eats away at the purchasing power of their invested dollars by requiring a higher rate of return on their investment. Which is the interest rate that homebuyers and homeowners will pay.
Next month I will explore mortgage program options available to offset higher interest rates.