The Local Source for News and Information Since 1980
Now that we have entered the 25th year of the 21st century it is a great time to review your credit report and if necessary implement a strategy to improve your credit. The Consumer Finance Protection Bureau requires that all three credit repositories provide one free credit report annually to consumers. Annualcreditreport.com is where you can access your report from TransUnion, Equifax, and Experian. Only the repositories themselves control access to your credit report. Other websites will promote a credit monitoring system or access to your credit score, usually for a fee. Most banks, credit card companies, or sites like Credit Karma will offer a free service that will disclose your credit score and monitor your credit for you. But looking at your credit report is necessary to make sure that what is there is correct.
Confirm that your personal information is correct. Are your payment histories correct and are the outstanding balances in line with your statements? Are accounts showing with balances that you know have been paid in full within the last 30 days? Most importantly, are there accounts showing open or with balances that you know have been closed or worse are not even yours?
Thirty-five percent of your credit score is determined by your payment history. Make sure that your report accurately reflects your payment history and is current and up to date. If you are currently late your credit score will drop ten to thirty points depending on your previous credit history. It could take three to six months to recover those points by making all payments on time. Credit scores go down dramatically at first and it takes time to gain them back.
The balance you owe on your credit cards in relation to your credit limit is thirty percent of your credit score. It is recommended that you manage your credit card balances by keeping the balance no higher than thirty percent of your credit limit. Paying your credit card balances in full every month is a better habit to get into.
Fifteen percent of your credit score is based on credit longevity or how long you have an open account. The longer the better. For this reason you should not close the credit card you have had the longest regardless of whether you use it or not.
If you are young you should open a credit card as soon as you are gainfully employed. This will be challenging since you have no credit history. A secured credit card is the easy answer. A secured card is a major credit card issued by Visa or Mastercard where you deposit funds into an account with them and they issue you a credit card with a credit limit equal to your deposit. A card with a three hundred dollar limit is the most common. Use the card to demonstrate your ability to manage credit appropriately. I suggest using it for gas since it is unlikely the balance will get over one hundred to one hundred fifty dollars keeping your credit utilization rate in mind. It will also generate a statement and bill due every month.
The last twenty percent consists of your credit mix and new credit with each impacting ten percent of your credit score. New credit is obvious as every new account will lower your score to some extent. How much depends on how long you have had credit and how many new accounts you have opened. Credit mix is how much revolving and installment credit you have in your history both current and in the past. Your credit history is a seven year look back of accounts both open and closed or paid in full. It is the mix of all these accounts that is taken into consideration.
Think of your credit score in the same way you think of your blood pressure. It should be monitored on a regular basis and corrective action taken when negative factors increase blood pressure or decrease credit scores.
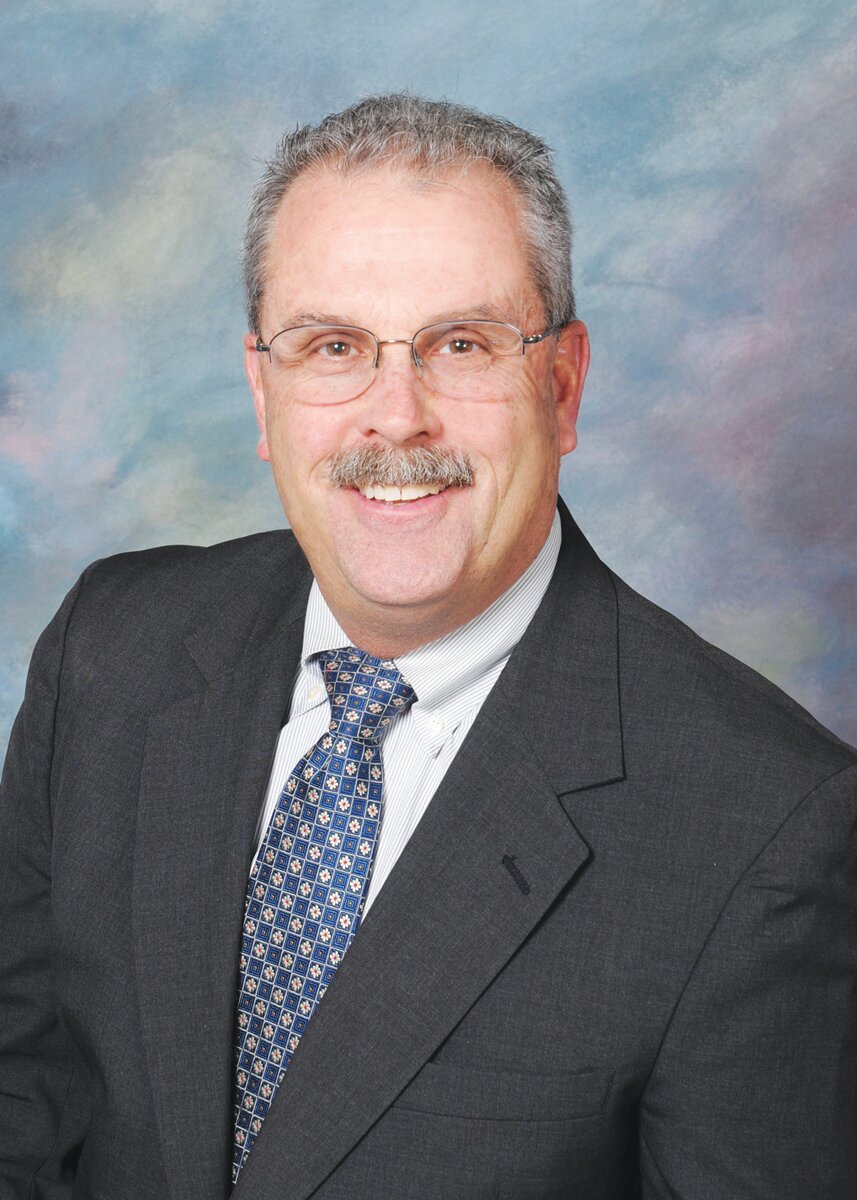
Mr. Rowe is Vice President/Lending for Bay CapitalMortgage Corp. with offices in Easton and Annapolis.He has lived in Caroline for his entire life and supportsthe county by volunteering in a variety of ways.He currently lives near Greenboro with his wife Jeanneand daughter Kelsey.